
Building Your Dream Home: Construction Loans & Progress Payments Explained
A quick heads-up: The information in this article is designed as a general educational guide only and does not constitute personalised financial, tax, or legal advice. Because everyone's situation is unique (and bank policies change frequently), we recommend speaking with a licensed Financial Adviser to see how this applies to your specific circumstances. For full transparency on our terms of service, how we are remunerated by lenders, and any specific situations where a fee may apply, please read How We Get Paid.
When you want a brand-new home, you generally have two choices: buy a Turnkey package off-the-plan, or buy a section of land and build it yourself using a Construction Loan.
With a turnkey property, you pay your initial deposit upfront and literally do nothing until the house is finished. It is straightforward, hands-off, and requires very little cash flow management.
So why would anyone choose to go through the extra effort of managing a construction loan?
While managing your own build requires more active involvement, it offers two distinct advantages that turnkey packages simply cannot match.
1. Total control and customisation
Turnkey homes are often designed to be somewhat generic, allowing the developer to appeal to a broad market and protect their profit margins.
When you use a construction loan, you have complete control. The most effective way to start is to find a piece of land and work directly with a builder or architect to design a home that fits the site perfectly. They will walk you through crucial decisions like positioning the house for optimal afternoon sun, maximising useful features, and customising the floor plan to suit exactly how your family lives.
2. The potential to create equity
Property developers do not build turnkey homes for charity; they factor their profit margin and their holding costs into the final sticker price you pay.
(If a builder has given you a turnkey price and a separate land-and-build price, compare the two options in our Turnkey vs Construction Loan Calculator).
When a 'fixed-price' contract isn't actually fixed
Before a bank agrees to fund your build, they will require you to sign a Fixed-Price Building Contract. However, 'fixed' is sometimes a generous term.
Most building contracts contain PC Sums (Provisional Sums). A PC Sum is an estimated allowance for a cost that the builder cannot guarantee upfront before work begins.
This is exactly why, as your mortgage adviser, alongside your solicitor, we review the finance clauses of your building contract before you sign it—to identify these PC Sums and ensure you have the required cash contingency buffers in place to survive them.
The construction loan timeline
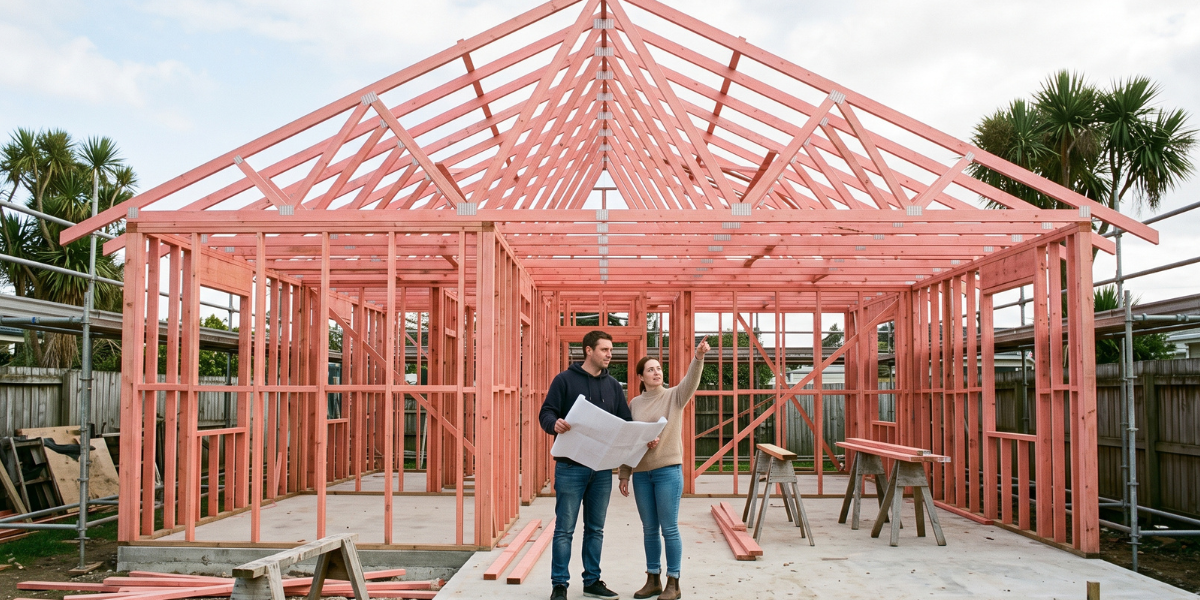
Unlike a standard mortgage, a construction loan is not handed over in one large lump sum on settlement day. It is released in stages (called progress payments) as the physical house is built.
The cash flow challenge: renting and building simultaneously
The biggest adjustment when managing a construction loan is your week-to-week cash flow, because you are effectively splitting your mortgage into two different loan structures:
1. The land loan
When you settle on the section, your mortgage officially starts. Because the land is a finished, tangible asset, this portion of your loan can usually be locked into a lower fixed interest rate. Depending on your cash flow needs, you can set this to Principal and Interest, or ask the bank for an Interest-Only term while the build takes place.
2. The build loan
The money used to physically construct the house is typically drawn down on a floating interest rate and set to Interest-Only. You only pay interest on the exact amount of money the bank has released to the builder so far.
However, every time a new milestone is reached (for example, the framing goes up and the roof goes on), the bank releases another progress payment. Your drawn loan balance increases, meaning your monthly interest payment becomes larger and larger every month until the house is finished.
If you are currently renting, you must budget to pay these escalating mortgage payments on top of your rent and normal living costs for the six to twelve months it usually takes to build.Crucial final steps: insurance and inspections
As you near the finish line, there are a few administrative hurdles you must clear before the bank will release the final progress payment and let you collect the keys:
- The insurance switch: During the build, the site is protected by the builder's Contract Works Insurance. However, the moment the council issues the Code Compliance Certificate (CCC), that insurance ends. You must immediately arrange standard house insurance and provide the Certificate of Currency to the bank before they will authorise the final drawdown.
- The independent building report: Before you authorise the final payment to the builder, we highly recommend paying for an independent building inspection to compile a snag list. We have seen fully signed-off new builds that still required significant remedial work. You have the most leverage to force a builder to fix minor defects before you hand over the final payment.
Building a home is one of the most rewarding financial moves you can make, but the cash flow and contract mechanics require expert navigation. At Home Loan Factory, we ensure your contingency buffers are in place, your contract finance clauses are safe, and your progress payments flow without a hitch.
Book a Free Strategy Session with a Home Loan Factory Adviser to Discuss Your Build Plans


