Should You Pay the Fee to Break Your Mortgage Early?

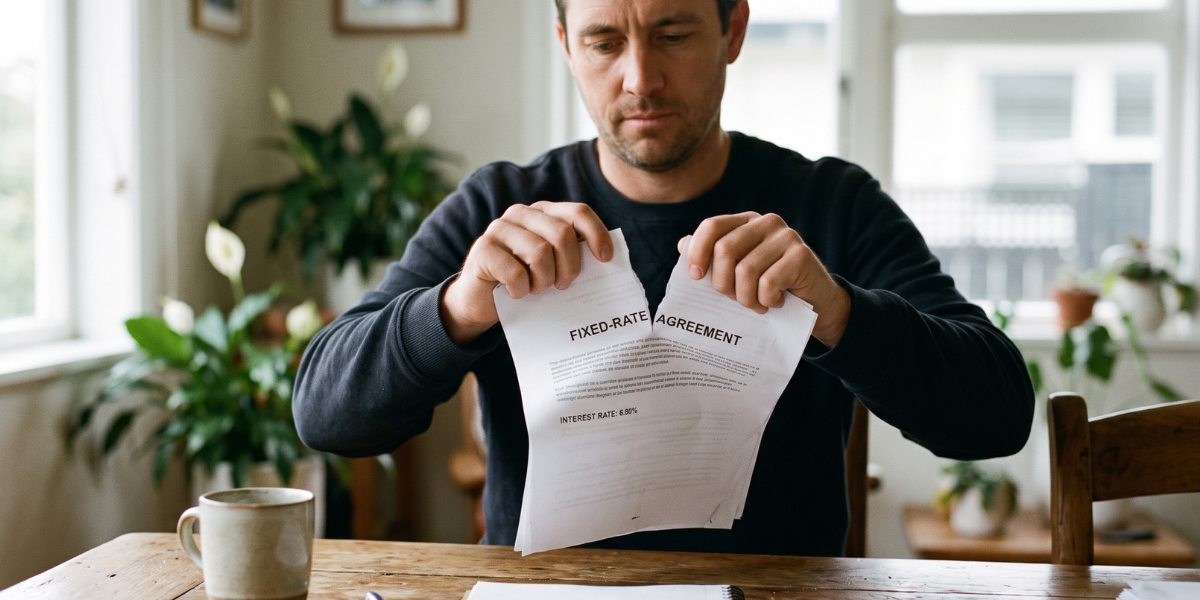
A New Zealand homeowner physically tearing a printed fixed-rate loan agreement paper in half at a dining table

A quick heads-up: The information in this article is designed as a general educational guide only and does not constitute personalised financial, tax, or legal advice. Because everyone's situation is unique (and bank policies change frequently), we recommend speaking with a licensed Financial Adviser to see how this applies to your specific circumstances. For full transparency on our terms of service, how we are remunerated by lenders, and any specific situations where a fee may apply, please read How We Get Paid.

When interest rates start falling, it can be frustrating to remain stuck on a fixed rate from a year ago. You might see lenders advertising rates in the mid-5% range, while your mortgage remains locked in at 6.8%.

The obvious solution is to break your fixed term early and switch to the lower rate. However, doing so triggers what is commonly known as a break fee—officially called an Early Repayment Adjustment (ERA).

A $3,000 or $5,000 charge can seem intimidating. Many homeowners see that figure, assume it is an arbitrary penalty, and simply ride out the rest of their fixed term. But an ERA is not a punishment—it is a calculated recovery of loss. And in some specific scenarios, paying that fee can make absolute mathematical sense.

Here is how break fees actually work, why online calculators get them wrong, and how to figure out if breaking your mortgage is worth the upfront cost.

Why do banks charge a break fee?

The bank is not generating a random penalty number just to stop you from refinancing. They are legally recovering an economic loss.

When you locked in your 6.8% fixed rate for two years, the bank did not simply use their own floating cash to fund it. They went to the wholesale money market and secured two years of funding for you at a specific wholesale 'swap rate'.

KEY INSIGHT: WHOLESALE SWAP RATES & THE CCCFA "NO PROFIT" RULE If you break your fixed contract early, the bank must take the money you repaid and return it to the wholesale market. If wholesale interest rates have dropped since you originally locked in your loan, the bank is forced to re-lend or sell that funding back at a loss.

Under the , lenders are legally prohibited from profiting on a break fee—they are only entitled to recover a reasonable estimate of their actual economic loss (plus a modest administrative fee), which is passed on to you as an Early Repayment Adjustment.

Why online break fee calculators are often inaccurate

If you search for a 'break fee calculator' online, you will find tools claiming they can estimate your specific penalty. Do not rely on them.

WARNING: THIRD-PARTY ONLINE BREAK FEE ESTIMATORS ARE GUESSWORK To calculate your exact cost to break, you need to know the specific wholesale swap rate the bank paid on the exact day you locked in your loan, the bank's internal funding margin, and how their treasury system applies present-value maths to your declining loan balance. Because nobody outside the bank has access to that proprietary data, generic online calculators can be out by thousands of dollars.

The only reliable way to know your true cost is to call your bank—or ask your mortgage adviser—to request a live break fee quote. It takes minutes, it is free, and it does not obligate you to break the loan.

The metric that actually matters: your break-even horizon

Once the bank gives you your exact break fee quote, the guessing game is over. Now, you just need to answer one crucial question: Will the interest I save on the new, lower rate pay off the break fee before my current term ends?

KEY INSIGHT: MEASURING YOUR BREAK-EVEN HORIZON This timeline is known as your break-even horizon.

For example, if it takes six months of lower mortgage repayments to recoup a $3,000 break fee, and you still have 14 months remaining on your current fixed term, breaking your mortgage early puts you ahead for the final eight months of the term.

Mortgage break fee calculator: finding your break-even point

Do not let the initial shock of an Early Repayment Adjustment trap you into overpaying interest.

Once you have your live break fee quote from your lender, plug it into our Break-Even ROI Estimator below. This calculator will instantly model your monthly interest savings, project your break-even timeline, and reveal exactly how much net financial benefit you stand to gain (or lose) by breaking your fixed term today.


The Break-Even ROI Estimator

Plug in the exact break fee quoted by your bank to get an indication of whether switching rates could potentially save you money overall.

Loan Balance $500,000
Current Fixed Rate 6.8%
Proposed New Rate 5.5%
Quoted Break Fee (From Bank)
$
Months Left on Current Rate 14 Months
Estimated Interest Saved Per Month
$0
The pure interest reduction indicated by dropping your rate.
Estimated Break-Even Horizon
0 Months
The approximate time it takes for your savings to offset the penalty.
Estimated Net Benefit
$0
Because your estimated break-even horizon is shorter than your remaining term, breaking your mortgage today could potentially result in a net financial benefit before your original contract ends.
*This calculator provides an indication only and does not constitute financial advice. It compares the pure interest reduction against the quoted break fee to estimate potential viability, assuming loan terms and principal repayment trajectories remain equal. Actual outcomes will vary. Always verify your break fee quote directly with your lender and seek professional financial advice before making changes.

Expert advice for your home loan, KiwiSaver, and beyond.