- Breaking a fixed rate can pay off if the interest saved on a lower rate recovers the break fee before your current term ends.
- Break fees, or Early Repayment Adjustments, recover the bank's wholesale funding loss, and the CCCFA prohibits lenders from profiting on them.
- Online break fee calculators can be out by thousands, so ask your bank or adviser for a free live quote instead.
- For example, if six months of savings recoup a $3,000 fee with 14 months left, you come out ahead for the final eight months.
A quick heads-up: The information in this article is designed as a general educational guide only and does not constitute personalised financial, tax, or legal advice. Because everyone's situation is unique (and bank policies change frequently), we recommend speaking with a licensed Financial Adviser to see how this applies to your specific circumstances. For full transparency on our terms of service, how we are remunerated by lenders, and any specific situations where a fee may apply, please read How We Get Paid.
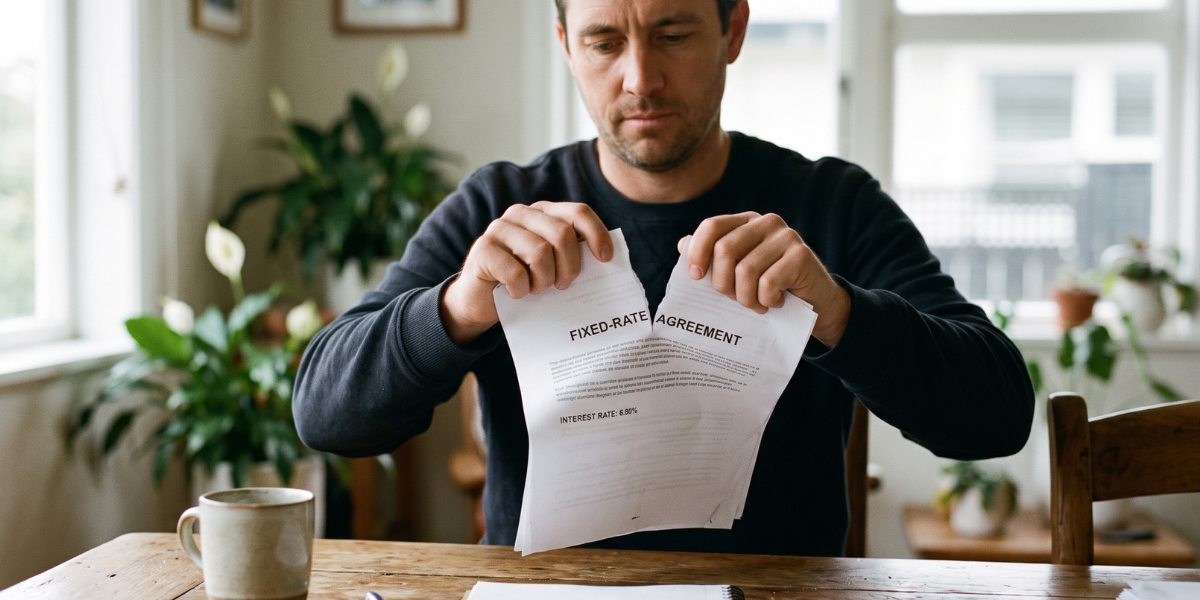
When interest rates start falling, it can be frustrating to remain stuck on a fixed rate from a year ago. You might see lenders advertising rates in the mid-5% range, while your mortgage remains locked in at 6.8%.
The obvious solution is to break your fixed term early and switch to the lower rate. However, doing so triggers what is commonly known as a break fee—officially called an Early Repayment Adjustment (ERA).
A $3,000 or $5,000 charge can seem intimidating. Many homeowners see that figure, assume it is an arbitrary penalty, and simply ride out the rest of their fixed term. But an ERA is not a punishment—it is a calculated recovery of loss. And in some specific scenarios, paying that fee can make absolute mathematical sense.
Here is how break fees actually work, why online calculators get them wrong, and how to figure out if breaking your mortgage is worth the upfront cost.
Why do banks charge a break fee?
The bank is not generating a random penalty number just to stop you from refinancing. They are legally recovering an economic loss.
When you locked in your 6.8% fixed rate for two years, the bank did not simply use their own floating cash to fund it. They went to the wholesale money market and secured two years of funding for you at a specific wholesale 'swap rate'.
Why generic break fee calculators fail (and what to use instead)
Most online break fee calculators do not work. They rely on basic retail rate comparisons and static balances, which can leave their estimates out by thousands of dollars.
To determine a bank’s actual cost to break, you have to look at wholesale swap rates—the rate on the day you fixed versus the replacement rate for your remaining term—and apply present-value calculations to your declining principal balance.
A better way to estimate your cost
We built our break fee estimation calculator specifically to solve this problem. By integrating historical wholesale swap curves and accounting for loan amortisation and publicly available bank specific break fee calculations, our tool provides a realistic, mathematically sound indication of your break cost before you approach your lender.
The golden rule remains: verify with a live quote
Use our calculator to see if breaking might be worth exploring. If the savings stack up, ask your mortgage adviser to pull an official live break fee quote from your bank. It is free, takes a few minutes to ask, with a reply within a few working days, and gives you the exact down-to-the-cent number before you commit to breaking.
The metric that actually matters: your break-even horizon
Once the bank gives you your exact break fee quote, the guessing game is over. Now, you just need to answer one crucial question: Will the interest I save on the new, lower rate pay off the break fee before my current term ends?
Mortgage break fee calculator: finding your break-even point
Do not let the initial shock of an Early Repayment Adjustment trap you into overpaying interest.
Once you have your live break fee quote from your lender, plug it into our Break-Even ROI Estimator below. This calculator will instantly model your monthly interest savings, project your break-even timeline, and reveal exactly how much net financial benefit you stand to gain (or lose) by breaking your fixed term today.