A quick heads-up: The information in this article is designed as a general educational guide only and does not constitute personalised financial, tax, or legal advice. Because everyone's situation is unique (and bank policies change frequently), we recommend speaking with a licensed Financial Adviser to see how this applies to your specific circumstances. For full transparency on our terms of service, how we are remunerated by lenders, and any specific situations where a fee may apply, please read How We Get Paid.
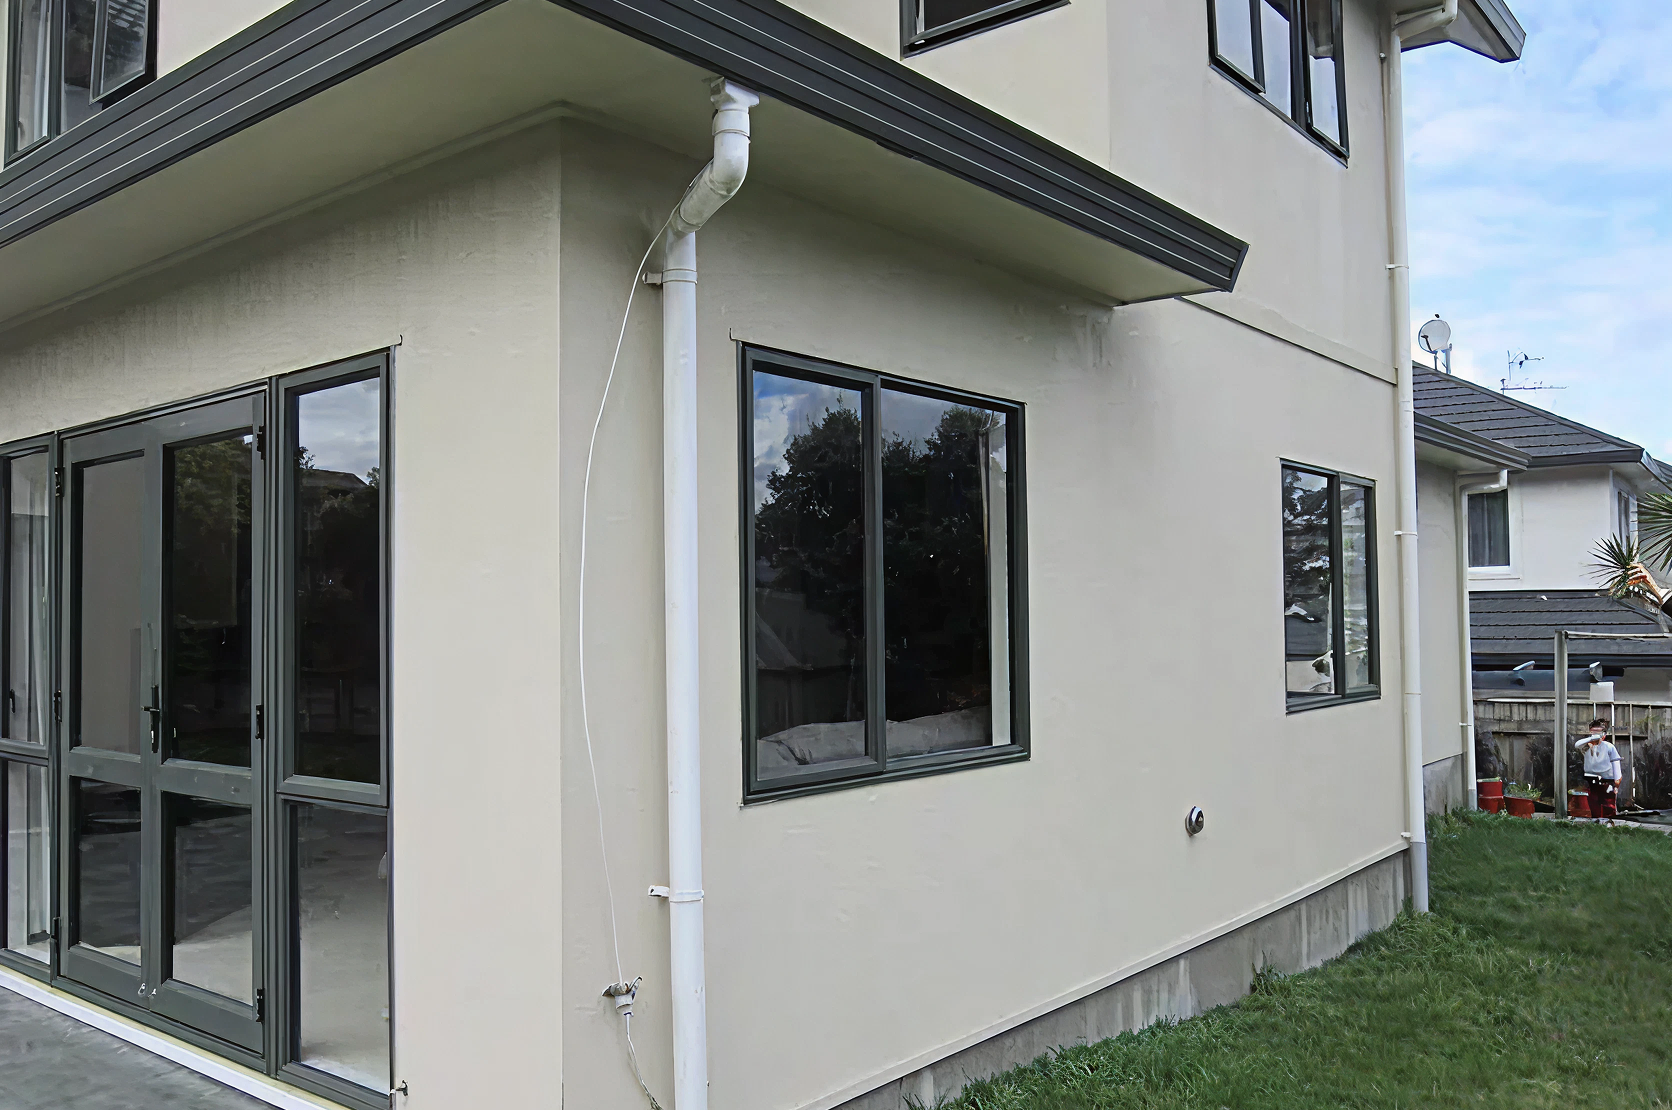
You have been scrolling through property listings, and suddenly you spot it: a massive, modern-looking house in a great suburb that is priced suspiciously below market value. You check the details, and there it is—a monolithic plaster exterior, built right in the middle of 1998.
Monolithic properties come up in discussions with clients all the time. While they were popular in the late 1980s, 1990s, and early 2000s for their sleek aesthetic and low build cost, they quickly became the centre of New Zealand’s leaky home crisis.
These homes often look like an incredible bargain on a real estate listing. However, that heavy discount is there for a reason: it reflects the significant underlying liability of the cladding.
Weighing the real risks
Before you start talking to a bank, you need to assess if the discounted purchase price outweighs the potential complications. Buying a plaster home from the high-risk era comes with three major risk factors:
- High repair costs: If the house has hidden moisture issues, fixing it is a major structural undertaking. A full house reclad can cost between $150,000 and $500,000, depending on the size of the home and the extent of the rotting timber underneath.
- Resale stigma: Even if the house is perfectly dry and has a clean weathertightness report, plaster homes carry a market stigma. You are buying the property at a discount today, but you will likely have to sell it at a discount in the future, and they often take a lot longer to sell on the open market.
- The gradual damage insurance exclusion: While securing a basic insurance certificate to satisfy the bank's mortgage conditions is usually achievable, the real danger lies in the fine print. Most standard New Zealand home insurance policies specifically exclude "gradual damage"—such as slow moisture ingress, weather degradation, and timber rot over time. This means if a monolithic house leaks, the insurer will likely deny the claim, leaving you completely responsible for the repair bill. As mortgage advisers, we cannot provide insurance advice, so you must speak to a licensed insurance broker to understand exactly what a policy excludes before you buy the property.
What is a monolithic home?
Monolithic refers to a type of construction where the exterior walls are covered with a seamless, textured plaster finish (often using fibre-cement sheets or polystyrene backing).
The historical issue was not just the plaster itself; it was a combination of building practices during that specific era (roughly 1987 to 2005):
Bank lending criteria and the weathertightness report
Getting a mortgage for a monolithic property built during the danger era is possible, but it requires meeting strict lender requirements.
When do you need a weathertightness report?
In most cases, if a bank agrees to consider the property, they will often request a specialist weathertightness report. Do not confuse this with a standard pre-purchase building inspection, which only covers visual defects. A weathertightness expert tests for hidden moisture behind the cladding using two methods:
Are there exceptions?
While a weathertightness report is the industry standard, some banks will lend without one. This exemption is highly lender-specific and typically only applies if you have a deposit of 20% or more, providing the bank with enough equity to absorb the risk. On very rare occasions, we have seen approvals without a report for buyers with a 10% deposit, but this is the exception, not the rule, and depends entirely on the specific property and the overall strength of the borrower's application.
Our stance on first-home buyers
While we can secure finance for these properties, we generally caution first-home buyers against purchasing high-risk monolithic homes.
First-home buyers relying on a 10% or 15% deposit already face strict lending criteria, and the Kāinga Ora First Home Loan scheme almost universally rejects 1990s plaster homes outright. More importantly, first-home buyers rarely have the capital reserves required to absorb a six-figure reclad bill or weather an uninsurable event.
The bottom line
A monolithic property can be a way to buy a large home at a discounted price, provided you complete comprehensive due diligence. If a property from this era has been well-maintained, has a clean weathertightness report, and the insurance exclusions are fully understood, it can be a viable purchase for experienced buyers or investors.
Before you put an offer on a plaster home, speak to your solicitor, a home insurance adviser, and your mortgage adviser. At Home Loan Factory, we know exactly which banks view monolithic homes favourably and which ones will decline them. We can help you structure your application in the most effective way.