A quick heads-up: The information in this article is designed as a general educational guide only and does not constitute personalised financial, tax, or legal advice. Because everyone's situation is unique (and bank policies change frequently), we recommend speaking with a licensed Financial Adviser to see how this applies to your specific circumstances. For full transparency on our terms of service, how we are remunerated by lenders, and any specific situations where a fee may apply, please read How We Get Paid.
When you are in the thick of buying a property, it can easily feel like you are juggling endless paperwork, contract conditions, and sudden upfront expenses.
One of the most common hurdles buyers encounter—especially if you have less than a 20% deposit—is the bank requesting a registered valuation.
If your mortgage adviser has just told you that a valuation is required, do not panic. It is a standard, routine part of bank lending policy.
Here is a practical guide on what a registered valuation is, why the bank requires one, and how the process works from start to finish.
What is a registered valuation?
Put simply, a registered valuation is an in-depth, independent assessment of a property's current market value, completed by a registered professional valuer.
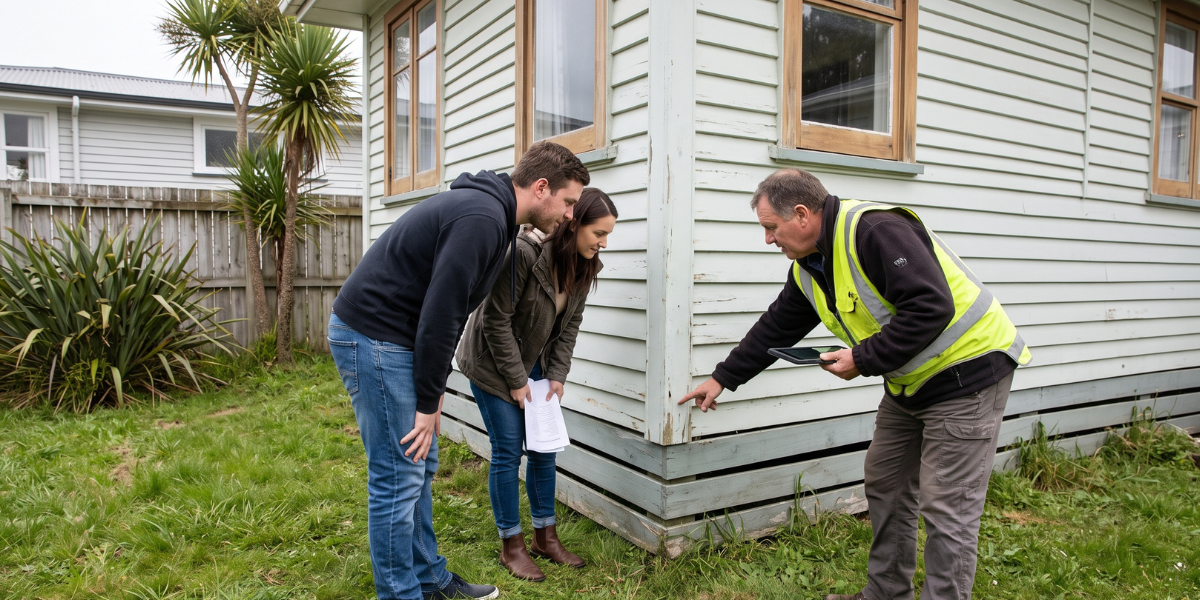
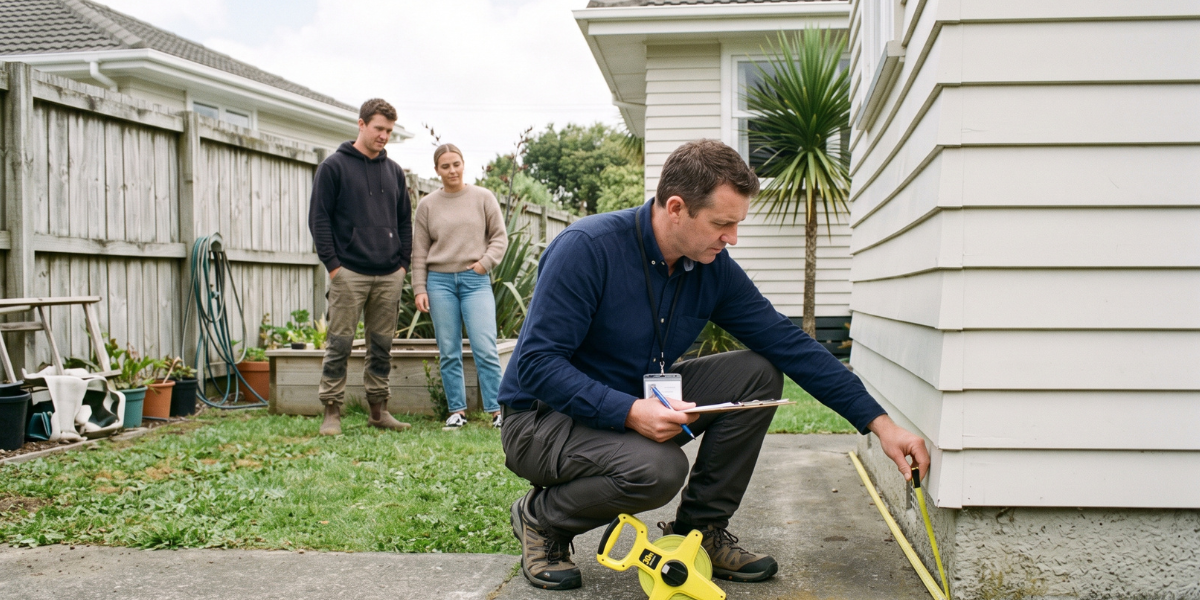
Unlike automated property estimates on real estate websites—which rely on computer algorithms and can vary significantly from on-the-ground reality—a registered valuer conducts a physical inspection of the property.
They measure the home, assess its overall condition, review local council planning zones, and benchmark the property against verified, settled sales of comparable homes in the immediate neighbourhood. They then deliver a comprehensive legal document establishing a definitive market valuation figure.
Why (and when) does the bank require one?
Banks are in the business of managing credit risk. If a borrower defaults on their home loan, the bank needs confidence that selling the property will fully recover the debt.
Lenders generally mandate a registered valuation in three distinct scenarios:
- Buying with less than a 20% deposit: When a bank lends at 10% or 15% deposit, their margin of safety is tight. They require absolute certainty regarding the property's baseline value.
- Private sales and family purchases: If you are buying a property privately from family, friends, or without an active real estate agency campaign, the bank wants independent verification that the price reflects true market value, rather than a discounted 'mate's rate' or an inflated agreement.
- New builds and off-the-plan builds: For construction lending, the bank requires an upfront valuation based on the architectural plans and specifications to confirm what the home will be worth once completed.
Cost and turnaround times
Because a registered valuation is a comprehensive legal document backed by professional indemnity insurance, it comes with an upfront cost:
- The cost: For a standard residential suburban property, expect to pay between $700 and $1,200. Rural lifestyle blocks, exceptionally large dwellings, or complex multi-unit titles typically cost more.
- The turnaround: The process involves scheduling an on-site visit with the vendor or agent, inspecting the dwelling, reviewing comparable land sales, and drafting the report. In most urban centres, this takes approximately 4 to 8 working days from the moment the invoice is paid. In smaller regional towns, it can occasionally take longer depending on local valuer availability.
What do valuers actually look for?
A valuer is not inspecting the property to evaluate your interior decorating tastes. When reviewing the home, they focus on verifiable property fundamentals:
- The dimensions of the dwelling, the usable floor area, and the total land section size.
- The age of the home, architectural design, and specific construction materials used (such as cladding and roofing types).
- The physical maintenance condition, interior layout, and the quality of permanent fixtures.
- Environmental and structural factors, including site contour, drainage, and council flood overlays.
- Location attributes, including school zonings, nearby amenities, and access to public transport networks.
Valuation versus a builder's report: the key difference
It is important to remember that a property valuer is not a qualified builder or structural engineer.
A builder's report investigates the physical and structural health of the building—such as checking for framing moisture, roof leaks, foundation stability, and plumbing defects.
A registered valuer inspects the property through the eyes of the broader market to determine its financial valuation figure.
However, there is an important crossover: if a valuer spots an obvious structural defect or significant maintenance issue during their inspection (such as sagging ceilings, extensive dampness, or visible foundation movement), they are legally obligated to record this as 'deferred maintenance' in their valuation report.
If the bank sees deferred maintenance flagged on the valuation, their credit team will almost certainly require a separate, specialist builder's report to confirm repair costs before issuing formal loan approval.
What happens if the valuation comes in low?
One of the most stressful moments in property purchasing is when you agree to buy a house for $800,000, but the registered valuation comes back at $765,000. This is known as a valuation shortfall.
Because banks calculate their maximum lending percentage against the lower of the purchase price or the registered valuation, a lower valuation means the bank will lend you less money.
If you encounter a valuation shortfall, you generally have three pathways:
- Renegotiate the purchase price: Through your conveyancing solicitor, you can present the valuation to the vendor and request that the purchase price be reduced to match the independent market valuation.
- Bridge the equity gap in cash: If you have surplus personal savings, an additional KiwiSaver buffer, or family assistance, you can make up the funding difference yourself.
- Exit the agreement via your finance condition: If the vendor refuses to adjust the price and you cannot bridge the shortfall, your solicitor can notify the vendor's legal team that finance is declined, allowing you to cancel the contract and retain your deposit.
How to order a valuation (the golden rule)
Need help navigating bank conditions or organising a registered valuation? Book a free strategy session with a Home Loan Factory adviser today.
Frequently asked questions
Can I choose my own registered valuer?
Usually, no. The major New Zealand trading banks require valuations to be ordered through accredited third-party platforms like Valocity or CoreLogic PropertyHub to prevent conflicts of interest. However, some smaller banks or non-bank lenders may allow you to choose a valuer directly, provided they are on that lender's specific 'approved panel'. Always check with your mortgage adviser before booking a valuer.
How long is a registered valuation valid for?
Most New Zealand trading banks consider a registered valuation valid for 3 to 6 months from the date of the inspection. If settlement extends beyond this window, the bank will typically require a valuer's certificate of confirmation or an updated valuation.
What is the difference between a council CV and a registered valuation?
A Council Capital Value (CV or RV) is a mass-appraisal figure generated for local council rating purposes, often updated only once every three years without an internal inspection. A registered valuation is an up-to-date, legally binding market assessment conducted in person by a qualified valuer.
Can I contest a low registered valuation?
While formal disputes are rare, you can ask your mortgage adviser or solicitor to submit a request for review if there are factual errors in the report (such as an incorrect floor area) or if relevant recent sales in the immediate street were overlooked.